Most countries adopted card payments and built from there. India looked at the cost of card terminals, the fees on every transaction, and the millions of small merchants who could never afford either and decided to skip the whole system. What it built instead now handles 49% of global real-time payments and runs on a printed QR code that costs nothing to produce.
For foreign tourists, this creates one immediate problem. Your card does not work at most of India's merchants. A UPI wallet can solve most of this problem, and getting one is simpler than most people expect.
Key highlights
- India has over 55 million UPI-enabled merchants. Most accept QR code payments only, not card swipes.
- Visa and Mastercard require a physical POS terminal. Most Indian merchants do not have one.
- UPI runs on a separate rail from Visa and Mastercard. Your card cannot interact with a QR code payment system.
- A UPI wallet loaded with an international card behaves like a local wallet at every QR merchant.
- International cards still work at large hotels, malls, and airport retailers, but not at most daily spending points.
- ATMs across India accept international cards, though fees and per-transaction caps apply.
- CheqUPI is free to join for all eligible nationalities, with a loading fee of 2.95% + applicable taxes and 0% merchant payment fee.
Why your card works in some places but not others
India has two payment tiers running side by side. The first is the card terminal tier: large hotels, airport retailers, upscale restaurants, and shopping malls. These all installed POS terminals before UPI dominated, and they still accept Visa and Mastercard normally.
The second tier is everywhere else. Auto-rickshaws, street food stalls, local markets, small guesthouses, temple town shops, and roadside vendors all moved to UPI QR codes. There is no card terminal to present, so your card has nothing to interact with.
Most tourists expect one of these two tiers and find the other instead. The gap between them is significant, especially outside major commercial districts.
A card that works at hotel checkout will fail at the chai stall outside the same hotel. Understanding this divide before arriving removes the frustration of unexpected declines.
How UPI works and why cards cannot plug into it
UPI is a payment rail built by the National Payments Corporation of India. It moves money directly between bank accounts and wallets using a unique payment address. No card network sits in the middle of this process.
A UPI payment goes from a wallet directly to a merchant's bank account using NPCI infrastructure. Visa and Mastercard have no role in this settlement.
The card network and the UPI rail are completely separate systems. Scanning a QR code with a foreign card produces no result.
This was a deliberate design choice. India built UPI to be free from international card network fees and accessible to merchants who could not afford POS terminals. The zero-fee QR model drove rapid adoption and closed the door on card networks at the point of sale.
The role of POS terminals
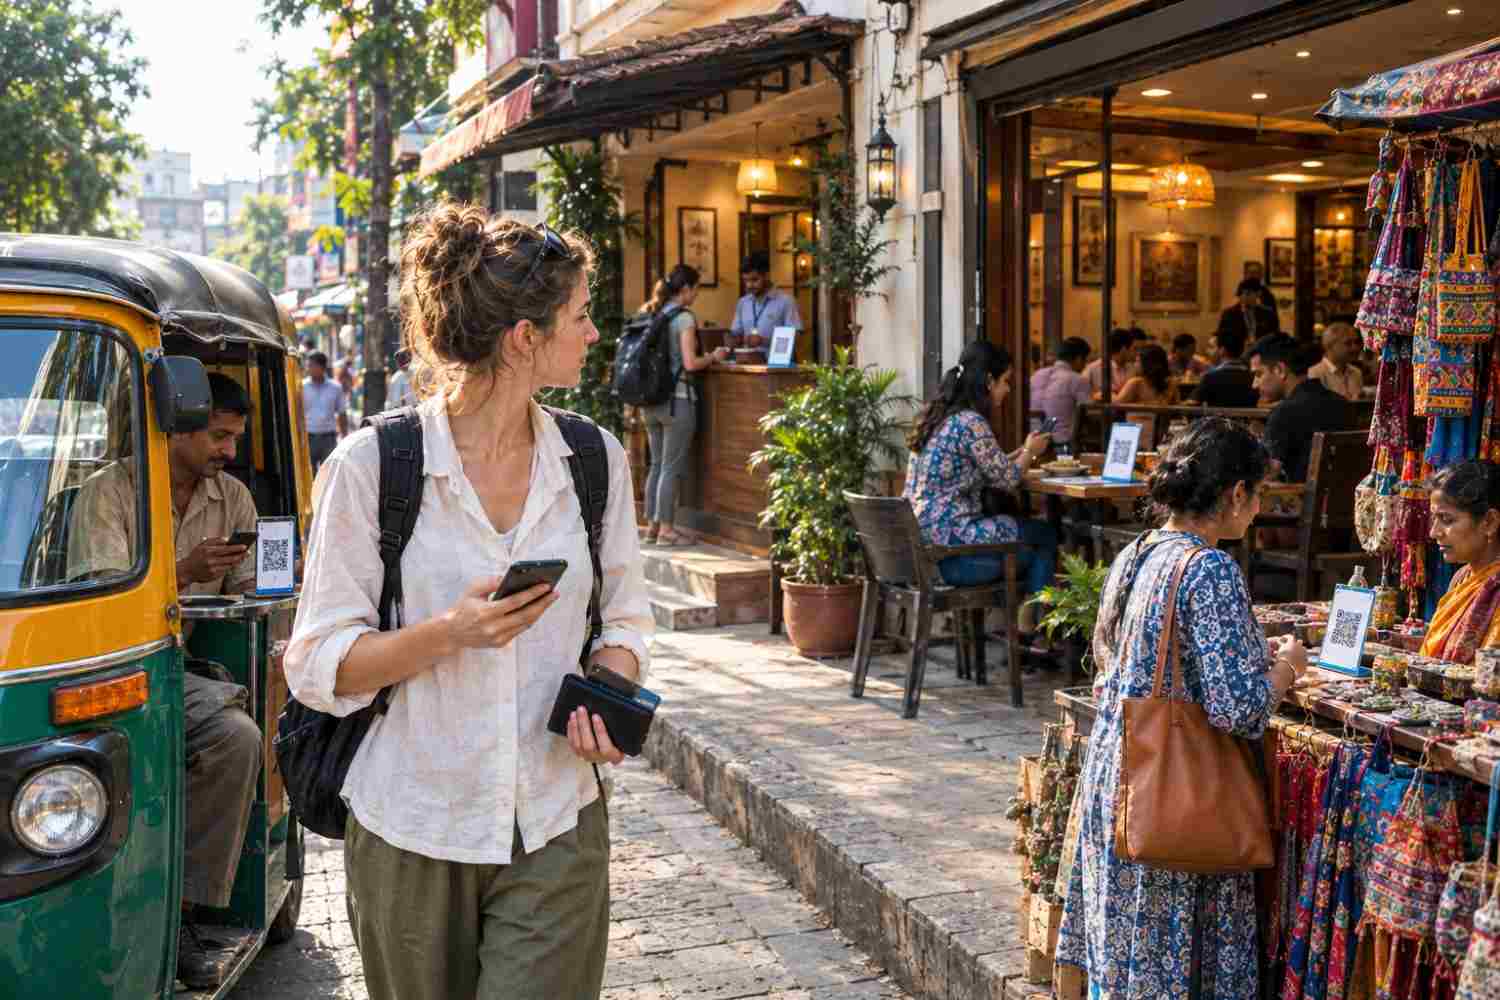
International cards work through a process that requires a physical terminal. The terminal connects to the Visa or Mastercard network, verifies the transaction, and settles the funds. Remove the terminal from this process and the card has no way in.
Most Indian small merchants never installed a card terminal. Hardware costs, monthly fees, and per-transaction charges made terminals unviable.
A printed QR code solved the same problem at zero cost. Once a merchant switches to QR-only, there is no incentive to add a card terminal back.
This is not a temporary situation. It is the settled design of India's payment landscape for the foreseeable future.
What foreign tourists can do
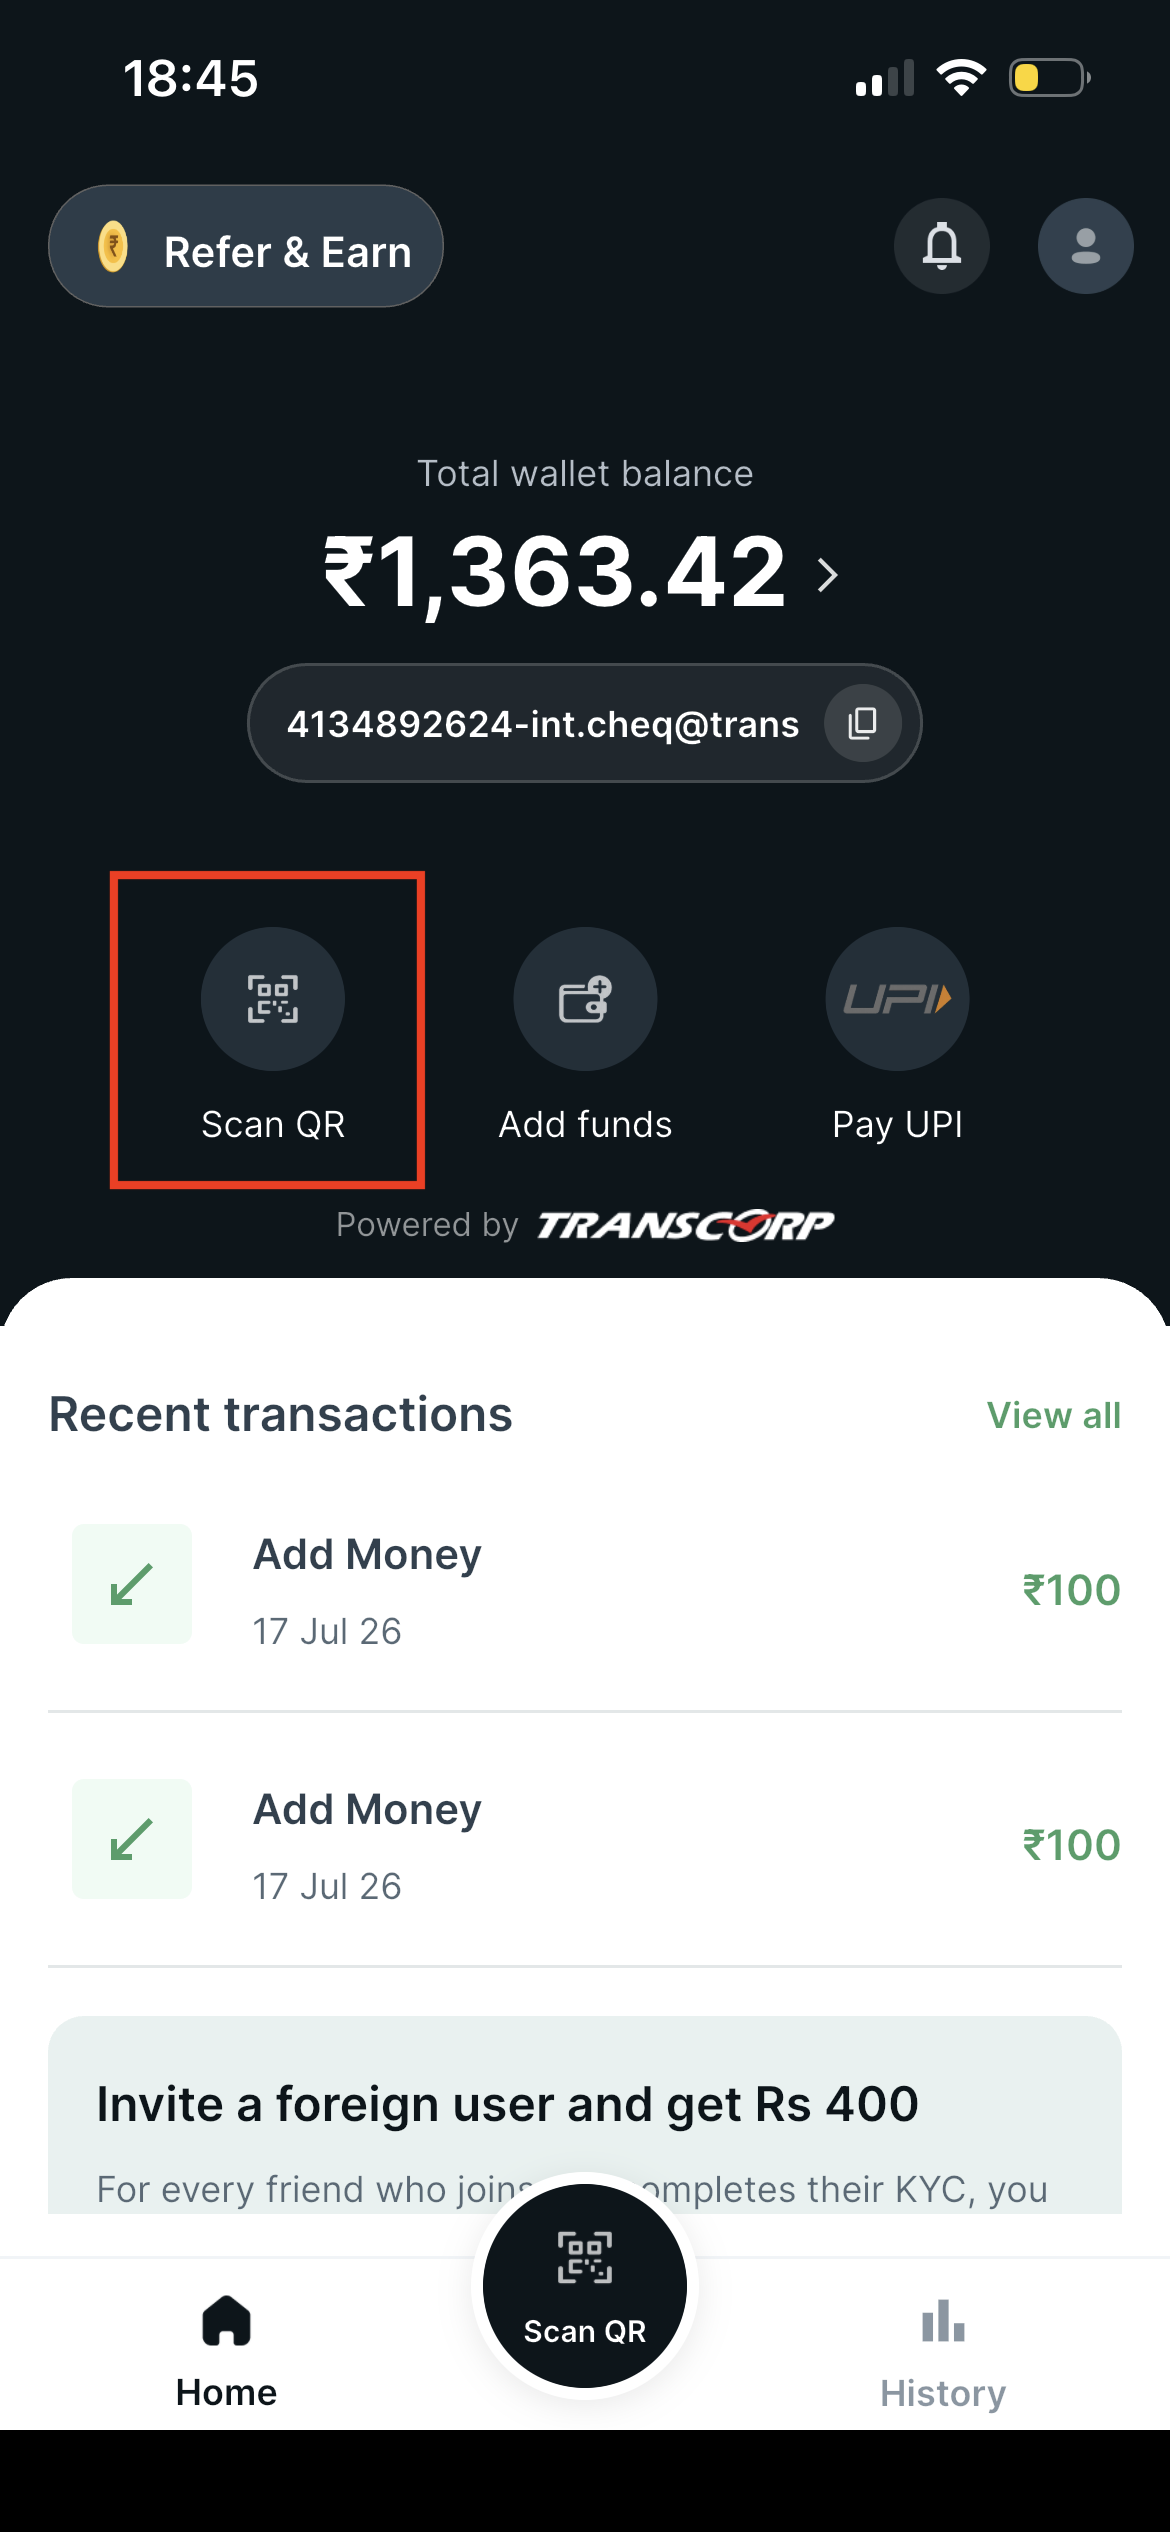
The only way to access UPI as a foreign tourist is through a UPI wallet loaded with INR using an international card. Once loaded, the wallet pays at any QR merchant exactly as a local wallet would. The card network is only involved at the loading stage.
No Indian bank account or Indian SIM card is needed. An internet connection and location access are required.
Registration requires your nationality; name as in your passport; and email address. An OTP arrives by SMS and WhatsApp, and WhatsApp works even if your SIM is not yet active.
You can download and register for a UPI wallet before your trip. Verification is completed in India after you arrive, not before. For a full walkthrough of how UPI works for foreign tourists, read our UPI payment guide for foreigners in India.
Where your card still works in India
Large hotels, international chain restaurants, airport retailers, shopping malls, and some monument ticketing counters still have POS terminals. These accept Visa and Mastercard normally. Any merchant that installed a terminal before UPI dominated can still process card payments.
Outside these environments, card acceptance drops sharply. Checking before a purchase avoids the moment of standing at a counter with no working payment option. As a general rule, if the merchant is a small independent business, assume UPI or cash only.
City-to-city differences also matter. Merchants in metro cities like Mumbai, Delhi, and Bangalore are more likely to have both options than merchants in smaller towns. Tourist-heavy areas like Rajasthan's forts and Kerala's backwaters have largely moved to QR-only at smaller vendors.
What to carry as backup
Even with a UPI wallet, carry Rs 5,000 to 10,000 (approx $52 to $104) in cash for vendors with no QR code or patchy connectivity. Many vendors refuse older-series or soiled banknotes, so ask for clean current-series notes when exchanging currency.
Airport money changers charge an 8 to 9% markup on exchange rates. Use ATMs from SBI, HDFC, ICICI, or Axis Bank instead for better rates.
These ATMs cap foreign card withdrawals at Rs 10,000 to 20,000 per transaction. They charge Rs 200 to Rs 335 (approx $2 to $4) per withdrawal. Your home bank adds a 1 to 3% foreign transaction fee on top.
For cash challenges foreign tourists face in India, read our guide on carrying cash in India for foreign visitors.
Staying safe with payments in India
When using a UPI wallet, always scan the merchant's QR code yourself rather than handing your phone to anyone. Confirm the payment amount on screen before approving. Keep your wallet app locked with its own PIN, separate from your phone's screen lock.
If a payment fails unexpectedly, check your wallet balance before retrying. Most failures come from connectivity issues or limit caps, not from fraud. Contact CheqUPI support via WhatsApp or at contactus@terrafin.tech if a payment fails for an unclear reason.
Watch for tampered QR codes at busy tourist sites. Some scams involve replacing a merchant's legitimate QR code with a different one.
Always verify the merchant name shown on screen after scanning before approving the payment. For payment scams to watch for in India, read our guide on scams foreign tourists need to be aware of in India.
Using UPI for different types of spending
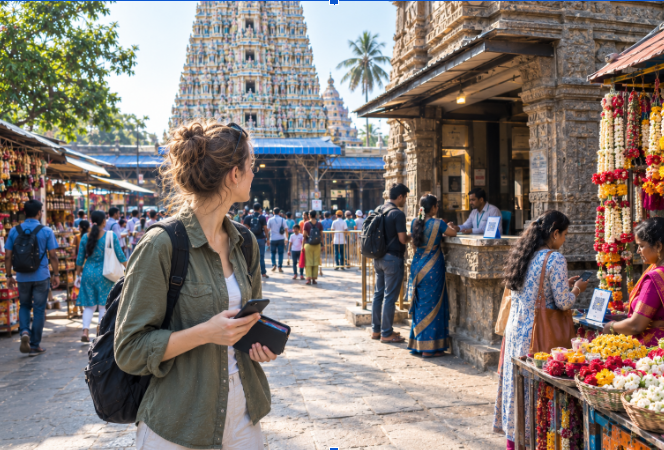
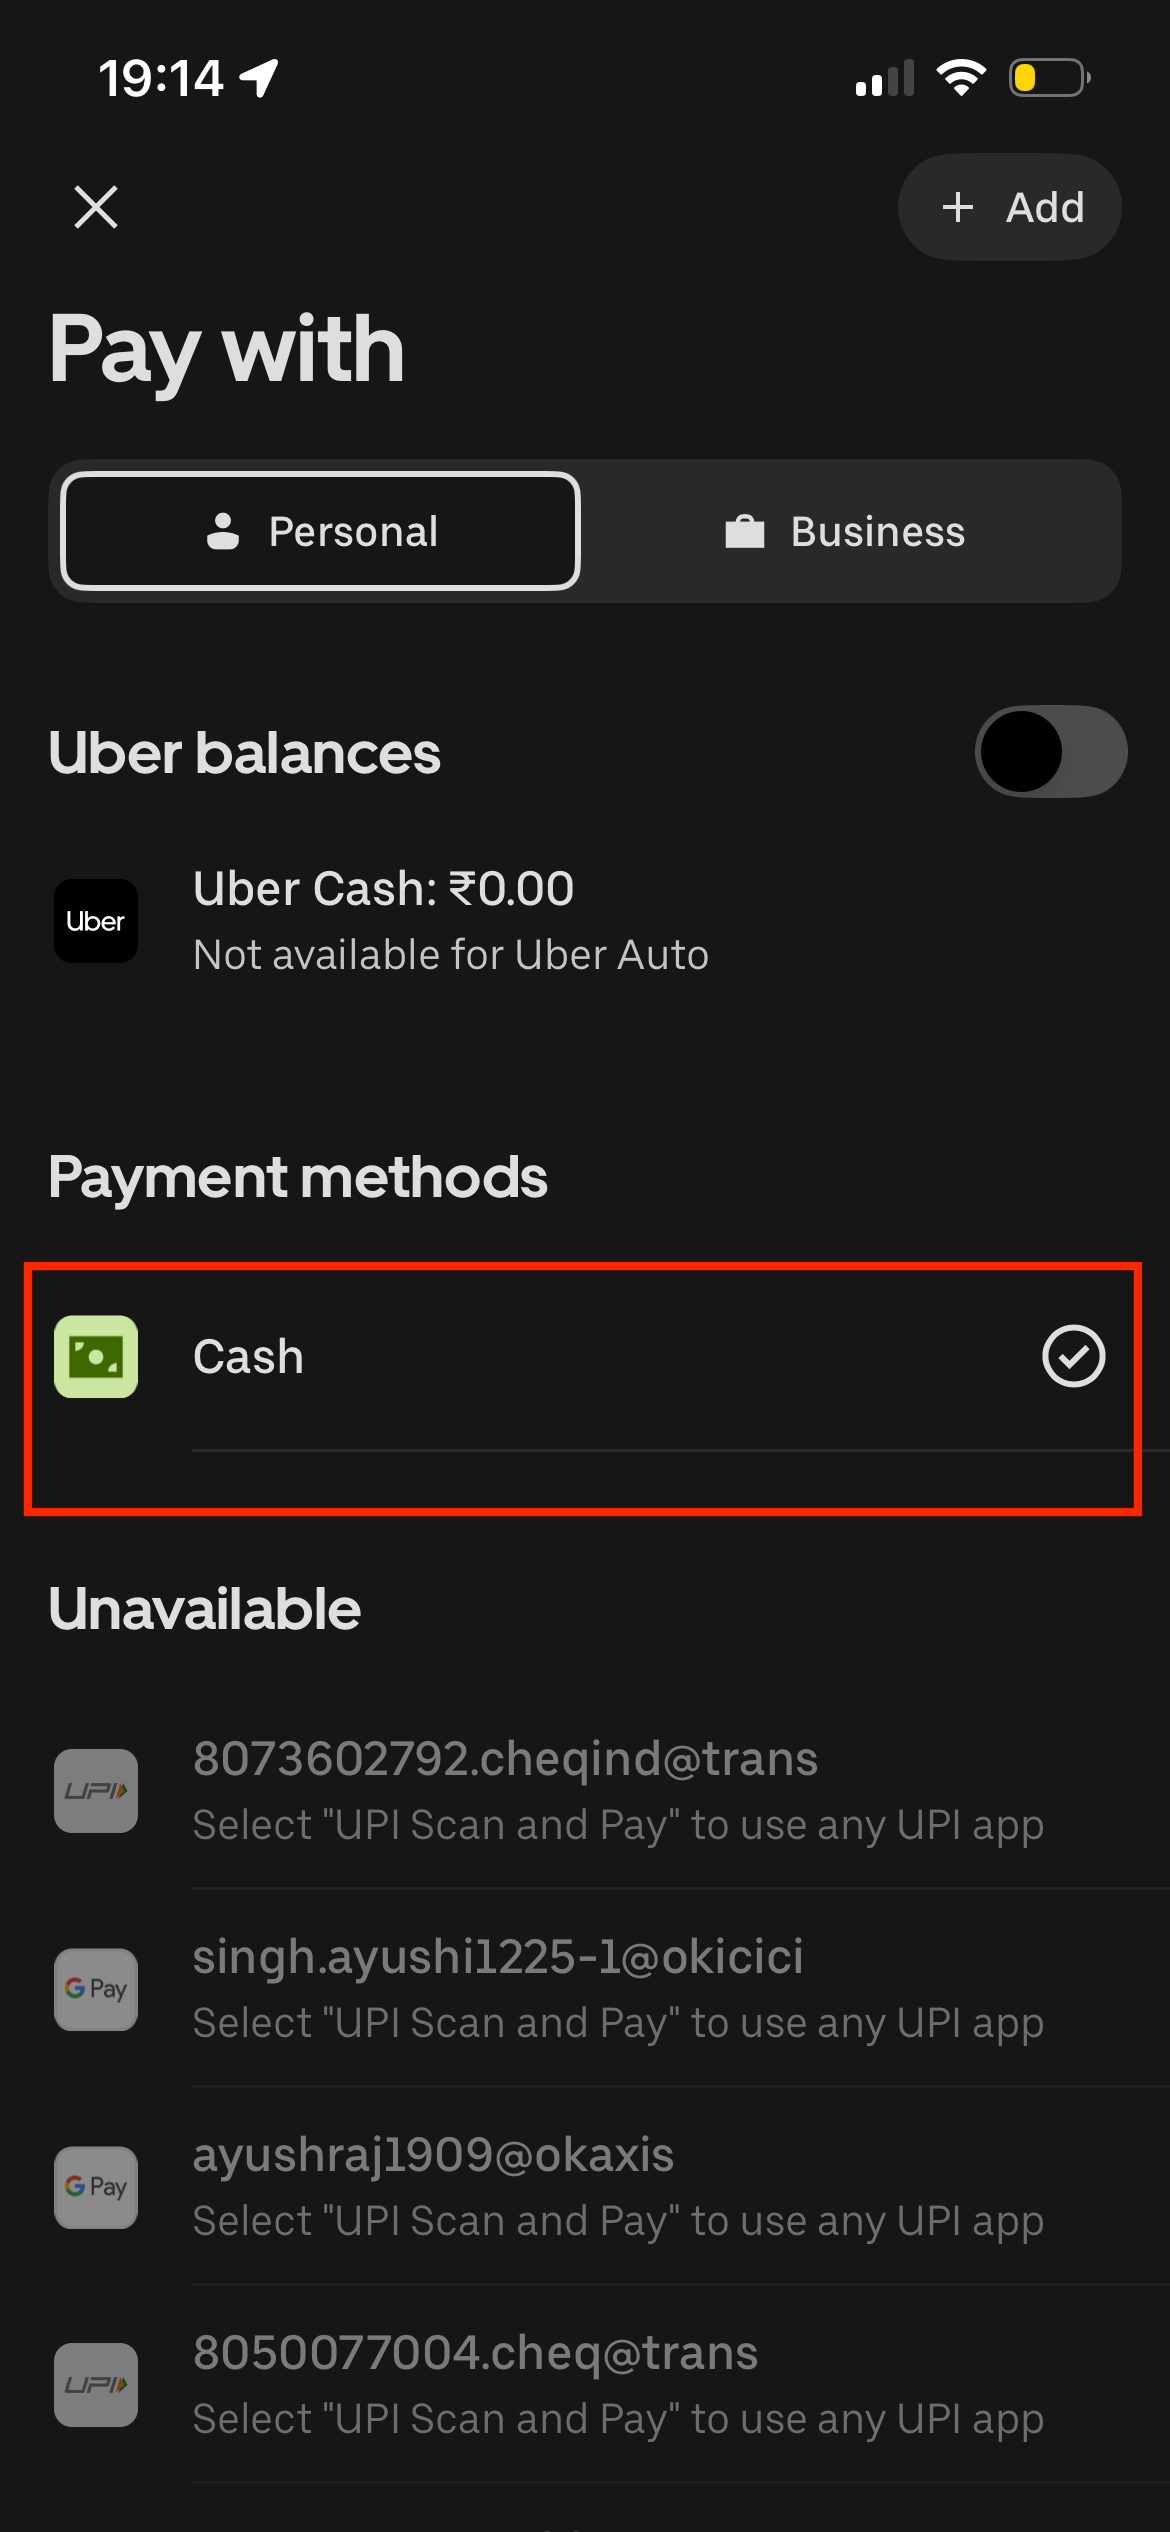
Transport: App-based rides like Uber accept regular UPI linked to a bank account, but not always prepaid wallets. Auto-rickshaws often use personal QR codes, which count as P2P transfers. CheqUPI supports person-to-merchant payments only. P2P transfers are not supported. Use cash for auto-rickshaws and personal QR codes.
Accommodation: Most hotels and guesthouses with a registered merchant QR code accept UPI wallet payments. Smaller homestays may use personal QR codes or cash only. Check before booking if cashless payment is important to your stay.
Food and markets: Restaurants and larger market stalls display merchant QR codes and accept wallet payments. Street food vendors and smaller stalls may be cash-only depending on location. In larger cities, most sit-down restaurants are UPI-enabled.
Monuments and entry fees: Larger monument ticket counters accept UPI and sometimes cards. Smaller sites, particularly in rural areas and smaller towns, are cash-only. Carrying cash specifically for monument entries avoids delays at popular tourist sites.
Conclusion
Visa and Mastercard fail at Indian QR codes because UPI was built outside their infrastructure entirely. The card networks require terminals, and UPI requires only a printed code. A UPI wallet loaded with an international card gives any foreign tourist access to India's full merchant network. The setup takes minutes, the loading fee is 2.95% + applicable taxes, and every merchant payment after that costs nothing. For any trip of more than a single day in India, this is the practical choice.
FAQs
1. Why doesn't my Visa card work at Indian QR code merchants?
UPI QR payments run on NPCI's rail, completely separate from Visa and Mastercard networks. Your card requires a POS terminal, and most Indian merchants do not have one.
2. Can foreign tourists use UPI in India?
Yes. A UPI wallet like CheqUPI lets foreign tourists load funds using an international card and pay at any of India's 55 million-plus QR merchants without a local bank account.
3. Where do international cards still work in India?
Large hotels, airport retailers, shopping malls, and chain restaurants with POS terminals. Most daily spending points, including street food, markets, and local transport, do not accept cards.
4. How do I pay at Indian QR code merchants as a foreign tourist?
Load a UPI wallet using your Visa or Mastercard. Once loaded, scan the merchant's QR code in the wallet app to pay. No card terminal needed.
5. Do auto-rickshaws accept UPI wallet payments?
Often not. Drivers frequently use personal QR codes, which count as P2P transfers. CheqUPI supports person-to-merchant payments only. P2P transfers are not supported. Carry cash for auto-rickshaws.
6. Can I use Uber with a UPI wallet in India?
No. Uber currently accepts regular UPI linked to a bank account, not prepaid wallets like CheqUPI.
7. How much does it cost to use a UPI wallet in India?
CheqUPI charges a loading fee of 2.95% + applicable taxes when you add funds. Every merchant payment costs 0%.
8. What happens if my card is declined at an Indian ATM?
Check that your card is enabled for international use. Indian ATMs cap withdrawals at Rs 10,000 to 20,000 per transaction. Try a lower amount or a different ATM if the first fails.
9. Can I use Apple Pay or Google Pay in India?
These work at merchants with NFC-enabled terminals, which are limited in India. They do not work at UPI QR code merchants.
10. How much cash should I carry in India?
Rs 5,000 to 10,000 (approx $52 to $104) covers transport and vendors where digital payments are not possible.
“CheqUPI turns your international card into a UPI wallet that works at 55 million-plus merchants across India. Download CheqUPI before your trip, complete activation after arriving in India, and pay most QR code merchant with confidence.”